
A commercial hail damage claim can look settled when the first insurance offer arrives. In this case, it was far from settled. The carrier’s initial estimate was $886,457.75. After our team documented the damage, built an independent estimate and negotiated with the insurer, the carrier’s updated number reached $2,226,712.88, an increase of 151%.
This case study walks through a real commercial property insurance claim for hail, wind and water-intrusion damage in the Midwest. We have removed identifying details to protect our client’s privacy, but the lessons apply to any business owner, property manager or board facing a large storm loss.
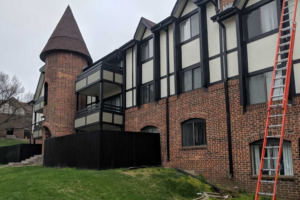 The challenge: a large storm loss and a low first offer
A severe storm brought hail, high winds and water intrusion to a commercial property with a 3-tab shingle roof. The damage was extensive, but the insurance carrier’s first estimate captured less than half of what the repairs would ultimately require.
The owners did not reach out for professional help until more than 21 months after the storm. That delay is common, and it creates real risk. Policy deadlines, fading evidence and carrier positions that harden over time can all work against a policyholder. The owners needed an advocate who could move quickly and still build a complete claim.
Our approach: document, price and negotiate
We treated the claim as a project with a clear path from the first call to the final check.
- Policy review. Our legal team reviewed the commercial policy to confirm coverage, limits and deadlines before any negotiation began.
- Damage documentation. We organized photos and project records so the carrier could see the full scope of hail, wind and water damage.
- Independent estimate. We built our own estimate of the repair cost, which came to about $2.38 million, instead of relying on the insurer’s numbers.
- Formal submission. We filed the proof of loss and supporting documents with the carrier.
- Negotiation and supplements. We pressed the carrier on the gap between estimates. Its offer rose in stages until it accepted about 93% of our estimate.
- Depreciation and follow-up. We requested release of withheld depreciation and kept the client updated through every step, with regular written status reports.
The results: a 151% increase in the insurance claim
The carrier’s number rose by more than $1.3 million, and the client received the first insurance payment about nine months after signing with Premier Claims.
| Measure | Result |
| Carrier’s initial estimate | $886,457.75 |
| Carrier’s updated estimate | $2,226,712.88 |
| Increase | $1,340,255.13 (151%) |
| Our independent estimate | About $2.38 million |
| Share of our estimate the carrier accepted | About 93% |
| Insurance payments issued by the carrier | More than $2.19 million |
The carrier’s first estimate equaled roughly 40 cents on every dollar of the final value. Complex commercial losses rarely resolve in weeks, but steady, well-documented work moved this one to a strong outcome.
 What this means for property owners
This case shows why a first offer should be treated as an opening position. If you own or manage a commercial building after a storm, keep these points in mind:
- Do not accept the first estimate by default. Carrier estimates often miss hidden roof, interior and water damage.
- Time matters. Policies have filing and legal deadlines, and evidence is easier to gather soon after the storm.
- Documentation wins negotiations. Clear photos, repair records and an independent estimate give you leverage.
- Ask about depreciation. Withheld recoverable depreciation is money owed to you once repairs are complete.
- It is not too late. Premier Claims was brought on almost two years after the loss and still produced a strong result.
Signs your claim may be underpaid
- The estimate is far below contractor bids.
- The carrier excluded areas that were visibly damaged.
- Roof repair is offered where replacement is needed.
- You received a denial or partial payment with little explanation.
Think your commercial claim was underpaid?
If your business or property was hit by hail, wind or water damage, do not assume the first offer is the final answer. Premier Claims reviews commercial property claims and helps owners understand what their policy may cover. Request a free claim review at [your website link] or call [your phone number] to talk with our team.
Every claim is different. Results depend on the policy, the damage and the carrier, and past outcomes do not guarantee future results.